
ExamVeda
Login
Home
81
A risk which is classified as its contribution to risk of portfolio is classified as
Discuss
Answer & Solution
Answer: Option D
Solution:
A risk which is classified as its contribution to risk of portfolio is classified as relevant risk. Relevant risk is the fluctuation of returns caused by the macroeconomic factors that affect all risky assets.
82
Chance of happening any unfavourable event in near future is classified as
Discuss
Answer & Solution
Answer: Option D
Solution:
Chance of happening any unfavourable event in near future is classified as risk. In broad terms, risk involves exposure to some type of danger and the possibility of loss or injury. In general, risks can apply to your physical health or job security. In finance and investing, risk often refers to the chance an outcome or investment's actual gains will differ from an expected outcome or return. Risk includes the possibility of losing some or all of an original investment.
83
A tighter probability distribution shows the
Discuss
Answer & Solution
Answer: Option B
Solution:
A tighter probability distribution shows the lower risk.
84
Stock which has higher correlation with market tend to have
Discuss
Answer & Solution
Answer: Option C
Solution:
Stock which has higher correlation with market tend to have high beta, more risky. High-beta stocks tend to be riskier but provide the potential for higher returns.
85
According to probability distribution of rates of return, a close outcome to an expected value is shown by
Discuss
Answer & Solution
Answer: Option C
Solution:
According to probability distribution of rates of return, a close outcome to an expected value is shown by more peaked distribution. Data that is more peaked is data that has a sharper peak compared to data with a more gradual slope. Gradual peaks indicate that your data rose steadily whereas a sharp peak indicates that your values increased rapidly.
86
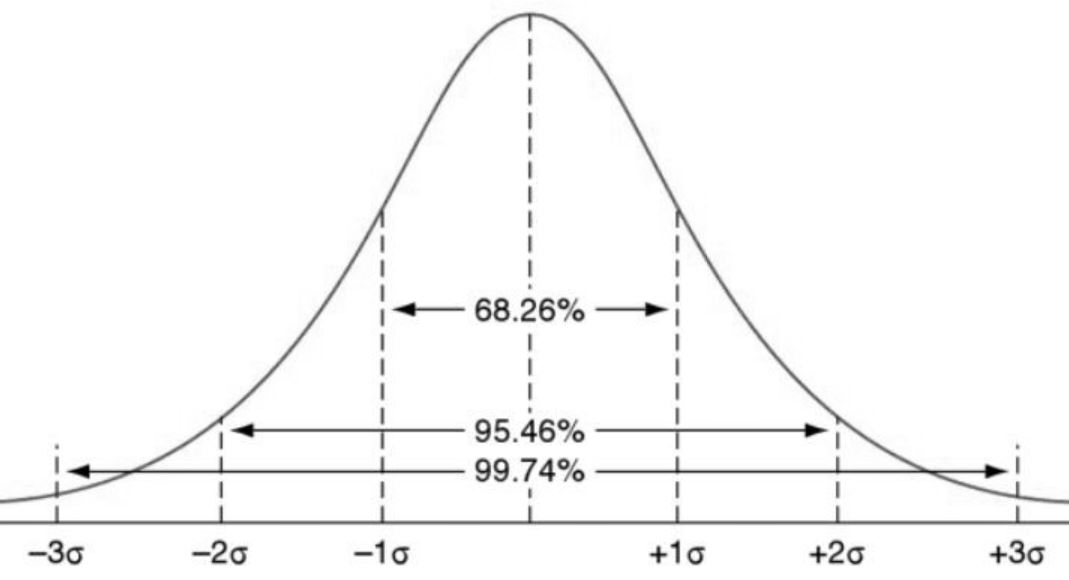
A range of probability distribution with 95.46% lies within
Discuss
Answer & Solution
Answer: Option B
Solution:
Financial Management mcq solution image
87
Coefficient of variation is used to identify an effect of
Discuss
Answer & Solution
Answer: Option D
Solution:
Coefficient of variation is used to identify an effect of risk and return. The coefficient of variation (CV) is a statistical measure of the dispersion of data points in a data series around the mean. In finance, the coefficient of variation allows investors to determine how much volatility, or risk, is assumed in comparison to the amount of return expected from investments.
88
In portfolio, beta of individual security in portfolio represented as their weighted average is classified as
Discuss
Answer & Solution
Answer: Option B
Solution:
In portfolio, beta of individual security in portfolio represented as their weighted average is classified as beta of portfolio. The beta of a portfolio is the weighted sum of the individual asset betas, According to the proportions of the investments in the portfolio.
89
Coefficient of beta is used to measure stock volatility
Discuss
Answer & Solution
Answer: Option B
Solution:
Coefficient of beta is used to measure stock volatility relative to market. A beta coefficient is a measure of the volatility, or systematic risk, of an individual stock in comparison to the unsystematic risk of the entire market. In statistical terms, beta represents the slope of the line through a regression of data points from an individual stock's returns against those of the market.
90
Probability distribution is classified as normal if expected return lies between
Discuss
Answer & Solution
Answer: Option A
Solution:
Probability distribution is classified as normal if expected return lies between ( + 1 and -1). A probability distribution is a statistical function that describes all the possible values and likelihoods that a random variable can take within a given range.